Flood Insurance for Georgia Homeowners and Renters
What Your Homeowners Policy Doesn't Cover
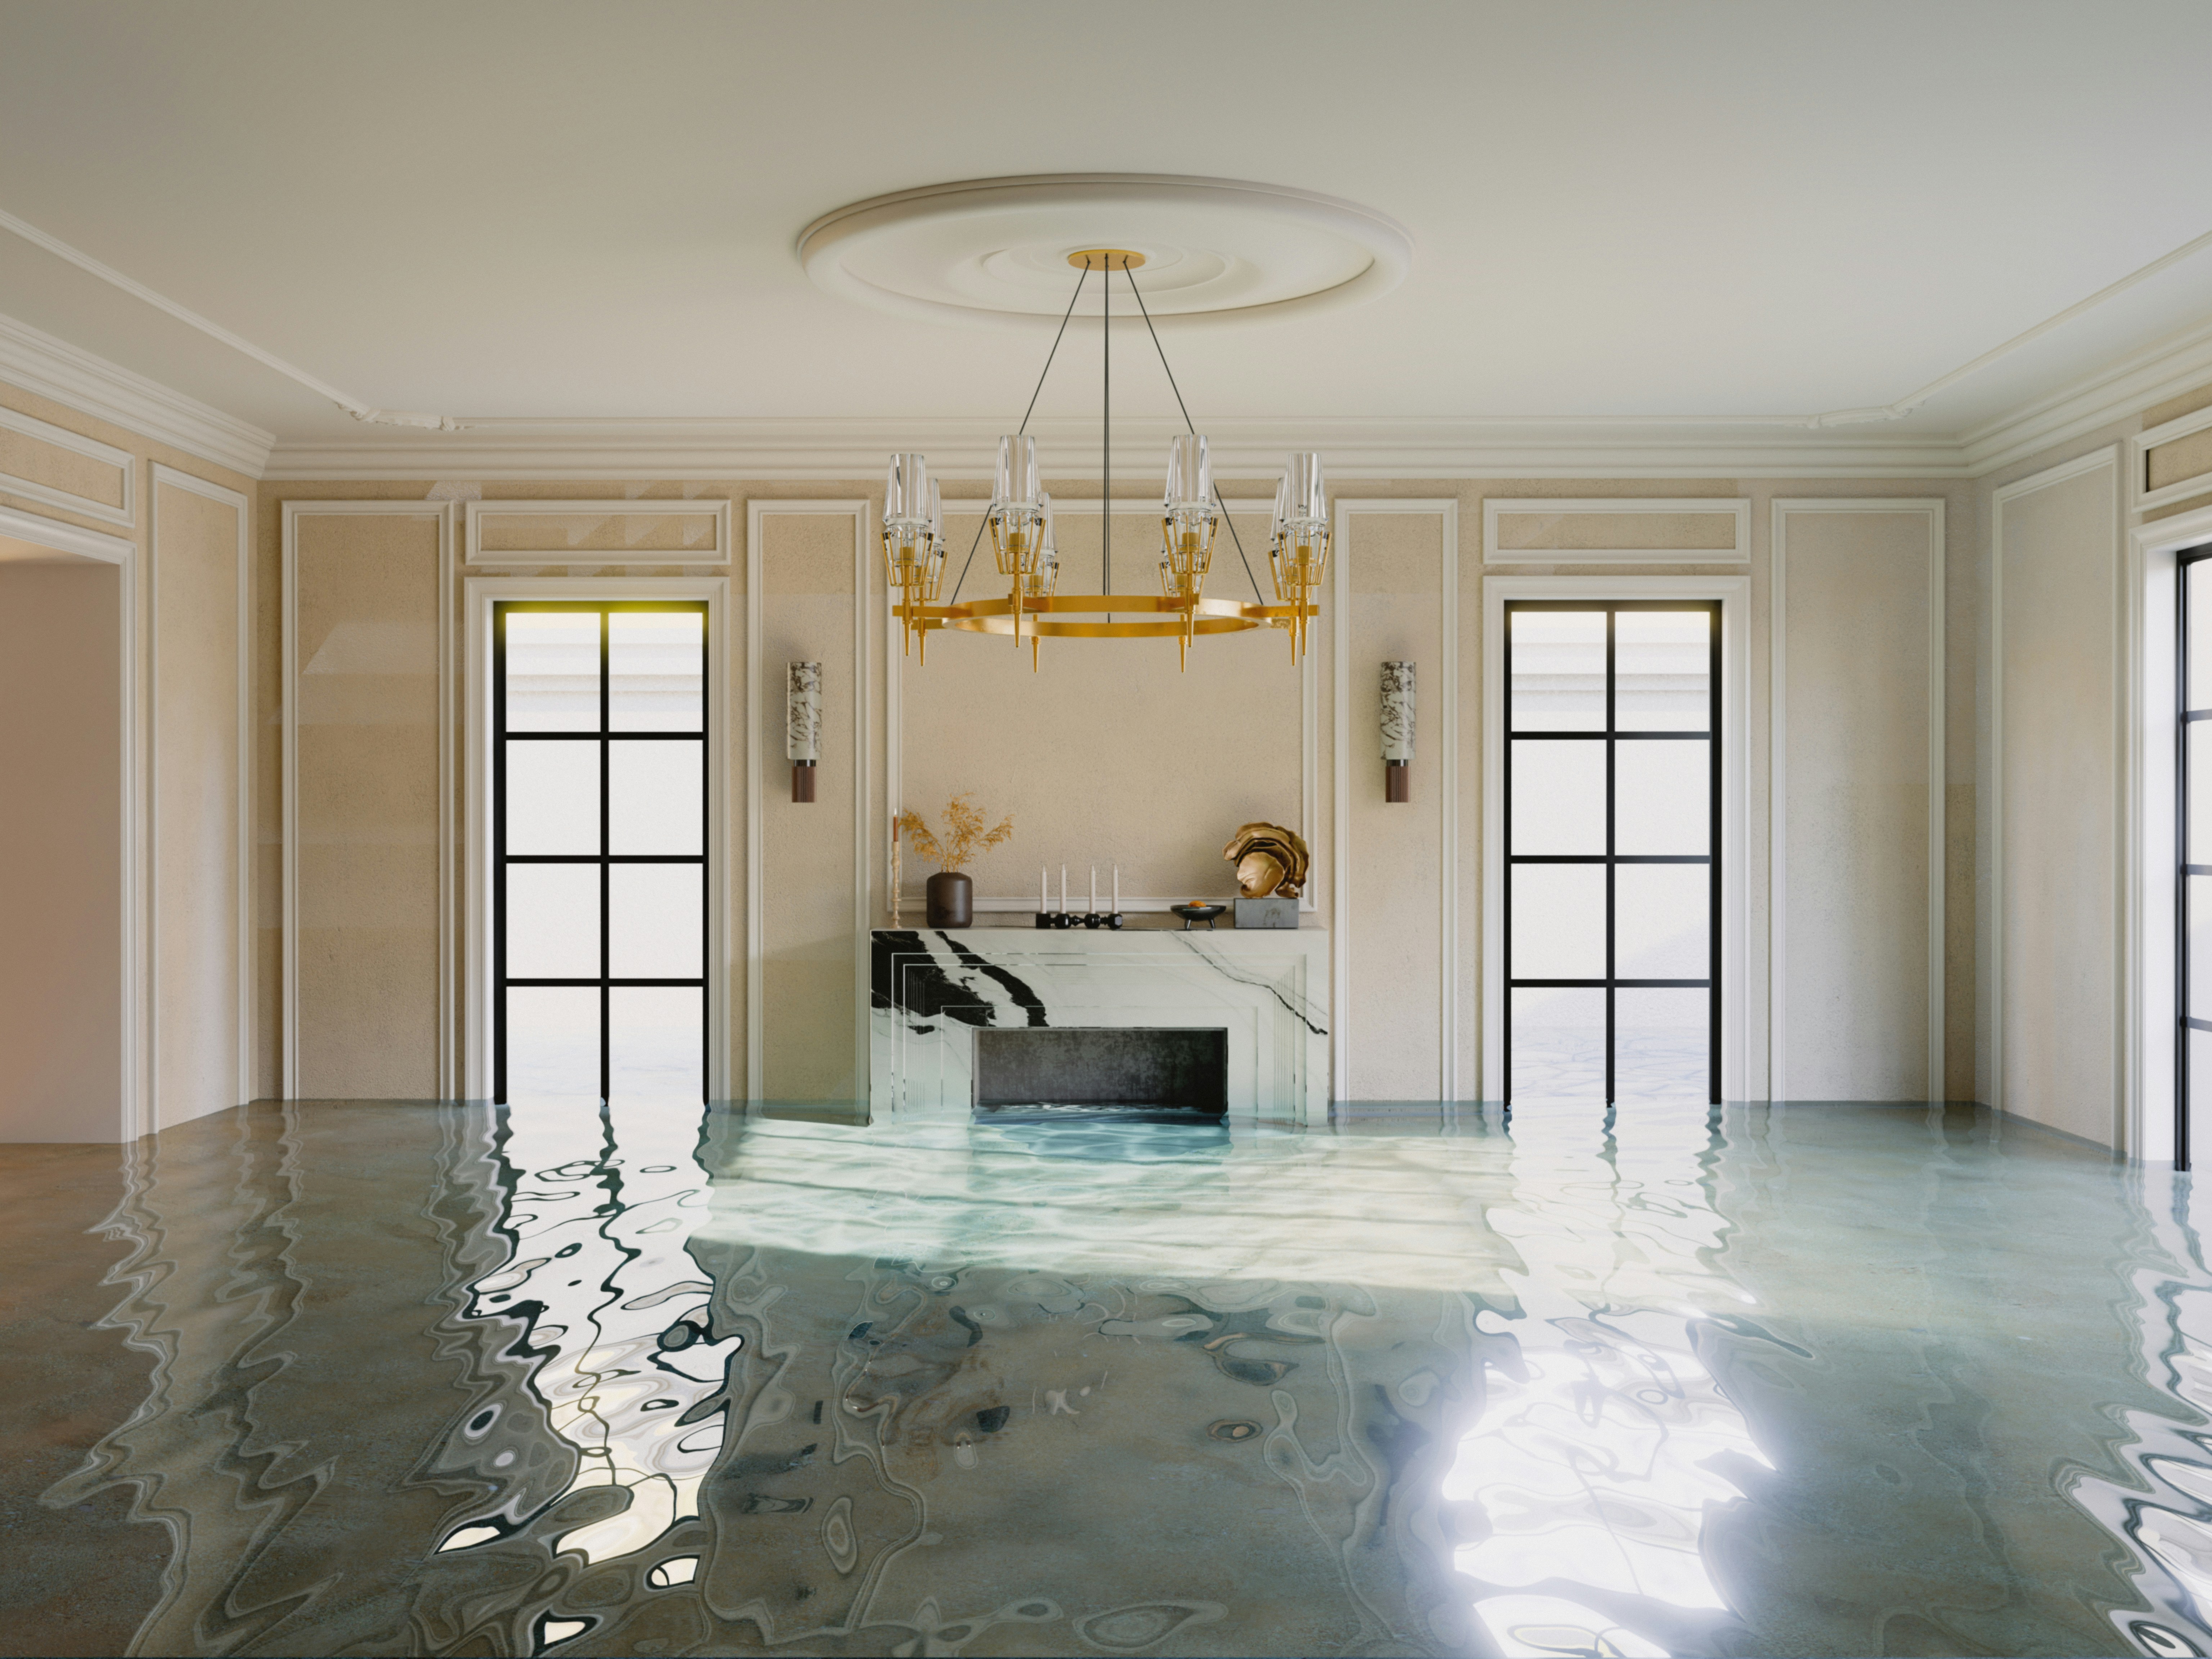
Flood damage is one of the most common misconceptions in insurance. Most homeowners assume their standard policy covers water damage from storms, overflowing creeks, or heavy rain — it doesn't. Homeowners, condo, and renters policies specifically exclude flooding caused by outside water sources. Without a separate flood insurance policy, any damage from rising water comes entirely out of pocket.
This gap matters in Georgia. The state sees significant rainfall throughout the year, and many DeKalb County properties sit near drainage areas, low-lying terrain, or older stormwater infrastructure that can be overwhelmed during heavy rain events. You don't have to be in a designated high-risk flood zone to experience flood damage — and you don't have to be a homeowner to need coverage.
-
40+ years in business
-
Family-owned and operated
-
On Lawrenceville Highway since 1989
-
Multiple carriers compared in one call
-
Auto, home, and umbrella under one roof
What Flood Insurance in Georgia Actually Covers
A flood insurance policy is structured differently from a standard home policy. Coverage is typically divided into two components: the building itself and the contents inside it. Both matter, and they're often purchased separately.
Building coverage generally includes:
- The foundation, walls, floors, and roof
- Electrical and plumbing systems
- HVAC equipment and water heaters
- Built-in appliances such as dishwashers and refrigerators
- Permanently installed flooring, including carpet and tile
Contents coverage addresses your personal belongings — furniture, clothing, electronics, and other items inside the home. If you rent, contents coverage is available to you even if you don't own the structure. Renters in flood-prone areas are often the most underinsured group when it comes to flood risk.
How Focus Insurance Group Helps You Find the Right Policy
Flood insurance in Georgia is available through two main channels: the National Flood Insurance Program(NFIP), administered by FEMA, and private flood insurance carriers. Each has different pricing structures, coverage limits, and waiting periods. As an independent agency, we work with multiple carriers and can walk you through the differences so you're choosing based on your actual situation — not just what's easiest to quote.
We've been helping Decatur-area residents sort through coverage questions from the same Lawrenceville Highway location since 1989. When you call us, you talk to someone who knows this area, understands the coverage, and will give you a straight answer about what makes sense for your property and budget.
What Our Clients Say About Working With Us
Flood Insurance Questions We Hear Most
Does my homeowners insurance cover flood damage?
No. Standard homeowners, condo, and renters policies exclude flooding caused by outside water — including storm surge, overflowing bodies of water, and heavy rain runoff. Flood coverage requires a separate policy.No. Standard homeowners, condo, and renters policies exclude flooding caused by outside water — including storm surge, overflowing bodies of water, and heavy rain runoff. Flood coverage requires a separate policy.Do I need to live in a flood zone to get flood insurance?
No, and many policyholders who file flood claims are outside designated high-risk zones. Flood insurance is available to any property owner or renter in a participating community, regardless of flood zone designation.No, and many policyholders who file flood claims are outside designated high-risk zones. Flood insurance is available to any property owner or renter in a participating community, regardless of flood zone designation.How long does it take for flood insurance to go into effect?
NFIP policies typically have a 30-day waiting period before coverage begins. Some private flood insurance carriers offer shorter waiting periods. If a named storm is already approaching, it's generally too late to purchase coverage that will apply to that event.NFIP policies typically have a 30-day waiting period before coverage begins. Some private flood insurance carriers offer shorter waiting periods. If a named storm is already approaching, it's generally too late to purchase coverage that will apply to that event.What's the difference between NFIP and private flood insurance?
The NFIP is a federally backed program with standardized coverage and limits — currently up to $250,000 for the building and $100,000 for contents. Private flood insurance can offer higher limits, broader coverage options, and sometimes more competitive pricing depending on your property's risk profile. We can compare both options for you.The NFIP is a federally backed program with standardized coverage and limits — currently up to $250,000 for the building and $100,000 for contents. Private flood insurance can offer higher limits, broader coverage options, and sometimes more competitive pricing depending on your property's risk profile. We can compare both options for you.Can renters get flood insurance?
Yes. Renters can purchase flood insurance for their personal belongings through the NFIP or private carriers. Your landlord's policy covers the building structure — not your furniture, electronics, or clothing. If your unit is on a ground floor or in a low-lying area, contents coverage is worth considering.Yes. Renters can purchase flood insurance for their personal belongings through the NFIP or private carriers. Your landlord's policy covers the building structure — not your furniture, electronics, or clothing. If your unit is on a ground floor or in a low-lying area, contents coverage is worth considering.
Talk to Someone Who Knows the Coverage
Flood insurance decisions involve real trade-offs between cost, coverage limits, and waiting periods. At Focus Insurance Group, we help Decatur-area residents and small business owners think through those trade-offs clearly, without pressure. Call us at (404) 633-3333 or stop by our office at 2373 Lawrenceville Highway, Monday through Friday, 9:00am to 5:00pm. We're happy to pull quotes and walk you through what each option actually covers.